Protect Your Home.
Preserve Your Insurance.
California wildfire hardening, insurability readiness, and evolving Zone 0 preparedness for high-risk properties.
California Wildfire Insurance Pressure Is Increasing
Across California, homeowners in wildfire-prone regions are facing unprecedented insurance pressure. Nonrenewal notices are increasing. Carriers are withdrawing from high-risk zones. The California FAIR Plan — the state's insurer of last resort — is experiencing record enrollment as traditional carriers reassess their wildfire exposure portfolios.
The California Department of Insurance continues to navigate the tension between consumer protection and carrier solvency. Commissioner Ricardo Lara's recent regulatory announcements signal that wildfire mitigation efforts may increasingly influence underwriting decisions — creating both opportunity and urgency for property owners in designated wildfire hazard severity zones.
The Safer From Wildfires framework represents California's evolving approach to connecting mitigation with insurability. Properties demonstrating comprehensive wildfire hardening may receive preferential consideration — but the standards are becoming increasingly technical, multi-layered, and property-specific.
For homeowners facing Zone 0 enforcement, increasing wildfire regulations, future mandatory wildfire mitigation requirements, concerns about losing property value, and wildfire rebuilding complications, the landscape is shifting rapidly. Insurance inspections are becoming more rigorous. Insurer mitigation requests are becoming more detailed. The window for proactive preparation is narrowing.
Why California Homeowners Are Receiving Wildfire Insurance Notices
Wildfire underwriting has fundamentally evolved. Insurers now deploy sophisticated wildfire risk scoring models that evaluate properties across dozens of exposure variables — from combustible vegetation proximity and ignition pathways to roof debris accumulation and structure ignition risk profiles. These assessments increasingly trigger insurer mitigation requests that extend far beyond traditional defensible space expectations.
When carriers conduct wildfire inspections, they evaluate factors most homeowners have never considered: ember intrusion vulnerabilities, vegetation overhang patterns, combustible transitional materials within the immediate structure zone, and compliance with evolving wildfire hazard severity zone classifications.
The Insurance Institute for Business & Home Safety (IBHS) continues to publish research demonstrating the complex relationship between property-level mitigation and structure survivability. Insurers reference these findings when evaluating wildfire compliance pressure and inspection-triggered mitigation requirements.
The result: homeowners receive notices citing defensible space deficiency, wildfire exposure concerns, and mitigation requirements they may not fully understand. The technical language — wildfire mitigation review, property hardening, wildfire compliance pressure — reflects an industry that has moved far beyond simple brush clearance expectations.
California Wildfire Regulations Are Rapidly Evolving
California's wildfire regulatory framework is expanding at an unprecedented pace. The CAL FIRE defensible space program now encompasses multiple zones with increasingly specific requirements. The California Board of Forestry's Zone 0 rulemaking represents a significant expansion of defensible space enforcement into the immediate structure-adjacent area — a zone most homeowners have never formally addressed.
California wildfire legislation continues to evolve. The California Wildland-Urban Interface Code establishes construction and material standards for properties in designated WUI zones. Meanwhile, Chapter 7A building material requirements define ember-resistant construction standards that apply to new construction and significant renovations in fire hazard severity zones.
Future wildfire mitigation mandates are anticipated. As California's wildfire seasons intensify and insurance market pressures mount, regulatory bodies are signaling expanded enforcement of defensible space, structure hardening, and wildfire preparedness documentation requirements. Properties that address these evolving standards proactively may be better positioned for both insurance retention and regulatory compliance.
Understanding Zone 0 & Defensible Space Pressures
Zone 0 — the ember-resistant zone extending from the structure outward — represents California's most significant expansion of defensible space requirements in decades. The CAL FIRE Zone 0 framework addresses combustible vegetation, structural attachments, and transitional materials within the immediate structure perimeter.
The Ready for Wildfire initiative outlines defensible space expectations across all zones. However, the technical complexity of Zone 0 compliance — particularly regarding vegetation overhang, combustible vegetation proximity, and ember intrusion vulnerability assessment — extends well beyond traditional brush clearance.
The Board of Forestry's ongoing rulemaking suggests that Zone 0 enforcement will continue to expand, creating increasing defensible space deficiency findings during inspections and wildfire compliance pressure for property owners who have not proactively addressed structure-adjacent ignition risks.
Wildfire Exposure Factors Insurers Increasingly Evaluate
Structure Ignition Risk
Insurers evaluate ember intrusion vulnerabilities, roof debris accumulation patterns, and combustible material proximity within the immediate structure zone. These factors increasingly determine underwriting outcomes.
Ignition Pathways
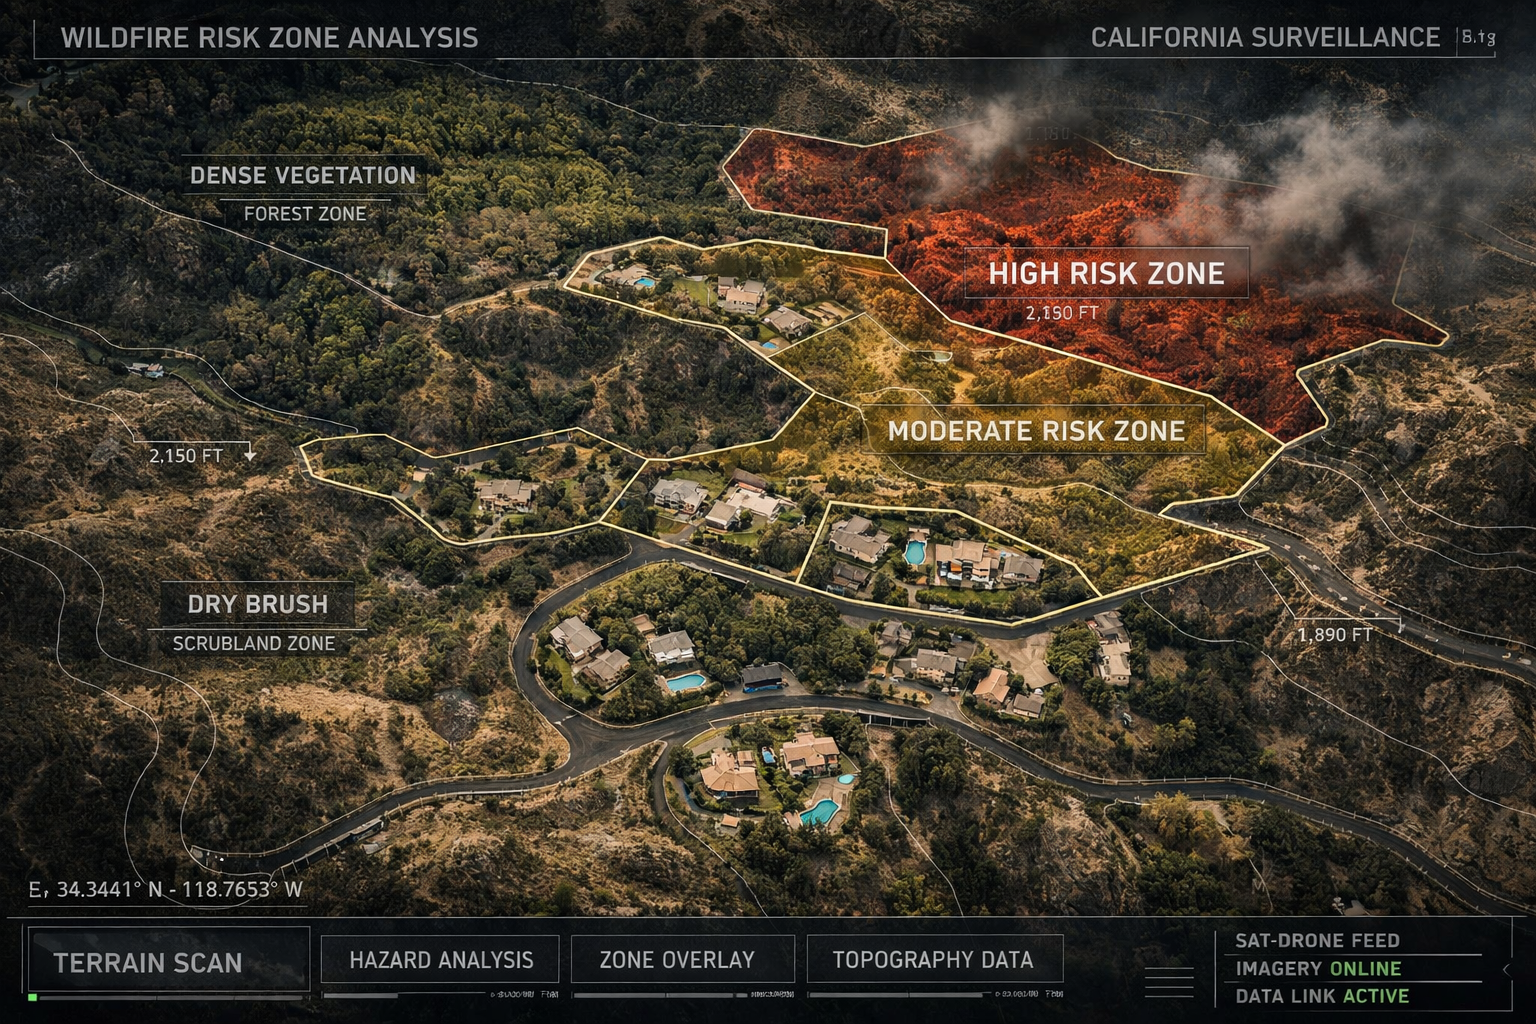
Wildfire exposure assessment now includes evaluation of continuous fuel pathways, vegetation overhang, and combustible vegetation connectivity between wildland areas and residential structures.
Wildfire Hazard Severity Zone
California's fire hazard severity zone maps are being updated, potentially reclassifying properties and triggering new mitigation requirements and insurance reassessments.
Wildfire Risk Scoring
The IBHS wildfire research informs carrier risk models that score properties on multiple exposure dimensions. Understanding these scoring factors is essential for addressing insurer concerns.
The Safer From Wildfires framework connects these evaluation factors to potential insurance benefits — but navigating the intersection of wildfire mitigation review, property hardening documentation, and insurer-specific requirements demands specialized assessment.
Many Homeowners Underestimate Wildfire Exposure Complexity
Many California properties contain unrecognized structure-adjacent ignition vulnerabilities associated with ember intrusion exposure, combustible transitional materials, and evolving wildfire mitigation expectations. The complexity of modern wildfire risk evaluation extends far beyond what most homeowners — or their landscapers — are equipped to assess.
Property-specific wildfire exposure involves multi-factor risk analysis that considers topography, prevailing wind patterns, vegetation density and type, structural materials, attachment points, and proximity to wildland fuels. Each property presents a unique combination of insurer-facing mitigation concerns that cannot be addressed through generic approaches.
Structure-specific vulnerabilities — from eave configurations and vent specifications to deck materials and fence attachments — create complex ignition pathway scenarios that insurers increasingly evaluate during wildfire inspections. Evolving compliance expectations mean that what satisfied an insurer two years ago may no longer meet current wildfire mitigation review standards.
The FEMA wildfire preparedness guidelines and Wildfire Prepared Home standards provide frameworks — but translating these into property-specific, insurer-facing mitigation documentation requires professional wildfire exposure assessment that accounts for inspection-triggered mitigation pressure and evolving compliance expectations.
Schedule Assessment
Property-specific wildfire exposure evaluation and insurability readiness review.
Schedule Assessment
Structure-Adjacent Ignition Risks
Ember-resistant construction standards, as defined by Chapter 7A building material requirements, address the structural components most vulnerable to wildfire ignition. However, existing properties often contain legacy materials and configurations that create unaddressed structure ignition risk.
Property hardening encompasses more than vegetation management. Wildfire home hardening addresses combustible transitional materials, attachment vulnerabilities, and ember intrusion pathways that connect wildland fire behavior to structural ignition. Wildfire mitigation documentation that addresses these factors is increasingly valuable for insurer-facing readiness.
The Wildfire Prepared Home framework and FEMA wildfire preparedness resources outline the scope of structure-adjacent risk factors — but professional assessment is increasingly necessary to identify property-specific vulnerabilities and develop insurer-facing mitigation strategies.
Preparing Before Mandatory Mitigation Requirements Expand
California's trajectory is clear: wildfire mitigation requirements will continue to expand. Future mandatory wildfire mitigation mandates are anticipated across multiple regulatory frameworks — from CAL FIRE defensible space enforcement to building code updates and insurance-linked mitigation standards.
Wildfire rebuilding pressures are intensifying. Properties damaged or destroyed in wildfire events face increasingly complex rebuilding requirements under current Wildland-Urban Interface Code standards. Proactive wildfire hardening may reduce both the risk of loss and the complexity of rebuilding compliance.
Wildfire preparedness initiatives at the state and local level signal expanded enforcement. The California Department of Insurance is increasingly connecting mitigation documentation to insurance availability — creating a direct link between property hardening and insurance retention. Properties that address wildfire exposure proactively may preserve both insurability and property value.
California Wildfire Compliance Is Becoming More Technical
Wildfire insurability is no longer a simple matter of clearing brush and trimming trees. The convergence of regulatory expansion, insurer sophistication, and evolving risk modeling has transformed wildfire compliance into a technical discipline that requires specialized assessment and documentation.
Generic landscaping alone may not address the specific insurer concerns identified during wildfire inspections. The Board of Forestry's evolving standards and regulatory announcements from the Department of Insurance indicate that wildfire mitigation review will continue to become more granular, more property-specific, and more technically demanding.
Professional wildfire exposure assessment is increasingly valuable — not as a replacement for homeowner awareness, but as a specialized evaluation that identifies property-specific vulnerabilities, documents mitigation readiness, and positions properties favorably for insurer review and regulatory compliance.
California FAIR Plan & Insurance Availability Concerns
The California FAIR Plan was designed as a temporary safety net — not a long-term insurance solution. Yet increasing numbers of California homeowners find themselves dependent on FAIR Plan coverage as traditional carriers withdraw from wildfire-prone areas. This dependency often signals broader insurability challenges that may affect property value and marketability.
The California Department of Insurance is working to stabilize the market through regulatory frameworks like Safer From Wildfires — which may allow properties demonstrating comprehensive wildfire hardening to access traditional insurance markets. However, meeting these standards requires documented, property-specific mitigation that addresses the full spectrum of wildfire exposure factors.
For homeowners facing nonrenewal notices, FAIR Plan dependency, or wildfire rebuilding complications, understanding the path back to traditional insurance requires navigating complex insurer expectations, evolving regulatory standards, and property-specific wildfire compliance pressure.
Wildfire Hardening & Insurability Readiness
Wildfire home hardening represents the intersection of structural resilience and insurance positioning. Property hardening that addresses insurer-facing wildfire readiness goes beyond vegetation management to encompass structural modifications, material upgrades, and comprehensive wildfire mitigation documentation.
The IBHS wildfire research demonstrates that structure survivability depends on addressing multiple vulnerability points simultaneously. Partial mitigation — addressing vegetation but ignoring structural vulnerabilities, or hardening the roof but neglecting vent protection — may not satisfy increasingly comprehensive insurer evaluation criteria.
Insurability readiness requires documented evidence of comprehensive wildfire mitigation. The Ready for Wildfire framework provides guidance — but translating that guidance into property-specific, insurer-facing documentation that demonstrates wildfire compliance readiness requires professional assessment and strategic mitigation planning.
Future Wildfire Mitigation Requirements California Homeowners Should Watch
California's wildfire regulatory landscape is not static. The Board of Forestry continues to develop expanded defensible space standards. The Department of Insurance is actively linking mitigation to insurance availability. And CAL FIRE enforcement is expanding in scope and rigor.
Wildfire preparedness initiatives at every level of government signal that compliance expectations will continue to escalate. Properties that address evolving standards proactively — rather than reactively after inspection findings or nonrenewal notices — may be better positioned to maintain insurance, preserve property value, and avoid the complications of post-loss rebuilding under increasingly stringent codes.
The convergence of insurance market pressure, regulatory expansion, and climate-driven wildfire risk suggests that wildfire mitigation will transition from voluntary best practice to mandatory compliance requirement for an increasing number of California properties. Early assessment and strategic preparation may provide significant advantages.
Schedule Your Wildfire Risk Assessment
Property-specific wildfire exposure evaluation, insurability readiness documentation, and strategic wildfire hardening consultation for California's high-risk properties.
Intended Use Notice & Disclaimer
FireShield is a private wildfire mitigation and compliance support company. FireShield is not a government agency, fire department, insurance company, insurance broker, or regulatory authority.
FireShield assessments, systems, and documentation are intended to support wildfire preparedness efforts only and do not guarantee:
- Insurance coverage, renewal, or insurability
- Government approval or regulatory compliance
- Prevention of wildfire damage or property loss
- Protection under all wildfire conditions
Property owners remain responsible for compliance, defensible space, emergency planning, evacuation decisions, and insurance coverage.